Independent insurance agency providing property, casualty, liability, life, surety bonds, and group insurance for personal and commercial clients.

We lead founder-led companies through the full M&A process—from prep to close—combining financial precision, buyer-side insight, and operational understanding to maximize your outcome.
Selling your business is one of the most important decisions you will make. MidCap Advisors manages the process confidentially and strategically so you never have to navigate it alone.
We bring industry insight, disciplined execution, and proven M&A expertise to handle complex transactions. Recognized for industry-leading analysis, exceptional valuations, and one of the highest close rates in the market, we guide every step—from preparation and financial modeling to connecting with buyers and managing negotiations—so you achieve the best outcome for both your business and your long-term goals.
We set clear goals and manage the full process so you stay focused on your business.
We dig into the general ledger to normalize financials and surface true drivers of value.
We support buyer diligence, so we know their priorities and prepare you to meet them.
We have sat in your seat and guide you with an owner’s perspective.
Strong buyer relationships and a top close rate deliver trusted outcomes.
We guide you through the entire transaction with structure, strategy, and transparency. While every deal is different, most engagements follow this proven path
Conduct pre-sale valuation analysis. Define go-to-market strategy. Prepare marketing materials Review valuation parameters. Identify and prioritize potential buyers.
Approach strategic and financial buyers. Receive initial interest and Indications of Interest (IOIs). Narrow the buyer pool to the most aligned parties
Conduct buyer meetings and Q&A sessions. Provide supplemental documentation. Pre-negotiate key terms and assess buyer fit Coordinate best-and-final offers or run a structured “auction” process.
Finalize preferred buyer. Negotiate Letter of Intent (LOI) and major deal terms. Align on employment agreements, rollover structure, and post-close plans.
Open data room and manage diligence requests Coordinate legal, accounting, and HR reviews Finalize Purchase Agreement Close transaction and support transition.
Week
Independent insurance agency providing property, casualty, liability, life, surety bonds, and group insurance for personal and commercial clients.
Third-party administrator (TPA) specializing in employee benefits administration, including COBRA, 401(k), pension, and flexible spending accounts.
Full-service insurance agency and consulting firm specializing in employee benefits, group health plans and financial consulting.
A leading provider of psychiatric medical care for elderly and disabled adults across long-term care facilities and hospitals in a metropolitan area has partnered with Health Catalyst Capital, a New York-based private equity firm focused on healthcare technology and tech-enabled services businesses. The transaction positions the company to accelerate growth by leveraging HCC’s healthcare network, strategic relationships, and value creation resources. MidCap Advisors was the exclusive financial representative for the company.
We had worked with a number of banks and advisory firms post our recovery from the effects of the 2009 financial crisis but none of these deals worked
We had worked with a number of banks and advisory firms post our recovery from the effects of the 2009 financial crisis but none of these deals worked out. We hired MidCap late in 2014 to assist us and not only did our transaction close the following year, but the valuation far exceeded any prior offer.
Their diligence created a phenomenal outcome for our group of companies and working with Gallagher is a win-win. Tony Leonard and Ryan Sanford were ex
Their diligence created a phenomenal outcome for our group of companies and working with Gallagher is a win-win. Tony Leonard and Ryan Sanford were excellent and professional, easy to work with, and reached back in a timely manner.
We had an excellent experience working with MidCap on the sale of our businesses. We did a rollup which involved the sale of five firms, simultaneousl
We had an excellent experience working with MidCap on the sale of our businesses. We did a rollup which involved the sale of five firms, simultaneously. We worked with Tony, Ryan and Brandon and thought they did a great job. They brought a lot of experience to the table and gave us some great advice.
We selected MidCap after interviewing three investment banks and are very happy with our decision. MidCap executed the transaction just as they said t
We selected MidCap after interviewing three investment banks and are very happy with our decision. MidCap executed the transaction just as they said they would and exceeded expectations of valuation.
Frank and Ryan guided us through a complex transaction involving five owners at different stages of their career and life. I couldn’t imagine going
Frank and Ryan guided us through a complex transaction involving five owners at different stages of their career and life. I couldn’t imagine going through the process without their support.
We fell in love with you guys, your team approach, and your whole enthusiasm and passion.
We fell in love with you guys, your team approach, and your whole enthusiasm and passion.
MidCap spent the time to understand our business and helped us select a buyer to achieve maximum value and to ensure a good fit for our producers and
MidCap spent the time to understand our business and helped us select a buyer to achieve maximum value and to ensure a good fit for our producers and employees. Their team continued to guide us through the complexities of diligence and documentation to ensure our deal got across the goal line.
I retained MidCap when I purchased York from AIG and was so delighted with their work that I hired them again five years later to represent me in sell
I retained MidCap when I purchased York from AIG and was so delighted with their work that I hired them again five years later to represent me in selling York in a private equity transaction.
We retained MidCap as our advisor because we were uncertain on how the market would value our agency and who would be the right partner for us and our
We retained MidCap as our advisor because we were uncertain on how the market would value our agency and who would be the right partner for us and our employees. Overall, their deal team was exceptional in obtaining management meetings, negotiating offers, and in getting us through the finish line. MidCap was able to exceed our pricing expectations and they helped us navigate uncharted territory. We appreciate their efforts and would highly recommend their services to any agency owner.
Several buyers had expressed interest in my firm but conversations weren’t progressing at the valuation expected. I got serious and hired MidCap and
Several buyers had expressed interest in my firm but conversations weren’t progressing at the valuation expected. I got serious and hired MidCap and we closed the transaction in less than 100 days. The MidCap analytics and analysis added several million dollars to my sale price and their help on the purchase and sale agreement was invaluable.
It’s an understatement to say it’s a difficult decision to sell an agency that has been in business for nearly a century. We turned to MidCap Advi
It’s an understatement to say it’s a difficult decision to sell an agency that has been in business for nearly a century. We turned to MidCap Advisors to help us assess the opportunity. MidCap has an excellent reputation as an advisor to the insurance industry and an extraordinary grasp of the bottom-line objectives of independent agencies.
I could not have completed the transaction without Midcap’s intelligence, expertise, and perseverance. I am energized by the potential for growth
I could not have completed the transaction without Midcap’s intelligence, expertise, and perseverance. I am energized by the potential for growth this will afford my practice. MidCap’s team was great.
Being a reproductive endocrinologist in private practice for several years, I connected with the Healthcare Group from MidCap Advisors because of thei
Being a reproductive endocrinologist in private practice for several years, I connected with the Healthcare Group from MidCap Advisors because of their experience in the healthcare industry and specifically in the fertility practice space. As investment bankers, they understood my goals and objectives and spearheaded the effort to find the best partner for me and my practice. I highly recommend MidCap Advisors if you’re thinking about the future of your practice. They are knowledgeable, understanding and care about the results, both financial and personal.
MidCap provided thoughtful and practical solutions to real-world problems, while simultaneously providing strategic guidance for our long-term plannin
MidCap provided thoughtful and practical solutions to real-world problems, while simultaneously providing strategic guidance for our long-term planning. They dug deep into our daily operations and provided impactful results that benefited our entire team – from sales to lab operations to billing.
As a busy physician whose focus was on my patients, when I decided to seek a merger partner I realized that I needed to have a knowledgeable and trust
As a busy physician whose focus was on my patients, when I decided to seek a merger partner I realized that I needed to have a knowledgeable and trustworthy advocate. For me, that need was fulfilled by MidCap Advisors. The process of identifying and evaluating a viable partner is time-consuming and my familiarity with it was limited. Going at it alone would have been detrimental, if not disastrous for my ongoing practice. Having the guidance and expertise of the people I worked with from MidCap Advisors proved to be invaluable and I highly recommend them.
We had engaged in a previous acquisition with another company and their team’s approach was the reason we backed out. Our company was acquired by a
We had engaged in a previous acquisition with another company and their team’s approach was the reason we backed out. Our company was acquired by a much larger organization and MidCap Advisors worked closely with us to make sure the transition went smoothly. Chip Loeb of MidCap Advisors was extremely helpful in working with our team to make sure all of our information was transferred properly and in a timely, efficient manner. Our company’s acquisition was one of the fastest HUB has seen, and everyone was pleased with the outcome. The team at MidCap is very professional and great to work with. MidCap went above and beyond and we are incredibly pleased with the outcome.
Our investors were ready for an exit and had an offer that I was not comfortable with. Our board allowed me to retain MidCap to pursue another option
Our investors were ready for an exit and had an offer that I was not comfortable with. Our board allowed me to retain MidCap to pursue another option and together we were able to raise equity and merge with another firm. We couldn’t have accomplished this without MidCap.
The team at MidCap provided expert, hands-on, senior-level negotiation and support before, during, and long after the transaction.
The team at MidCap provided expert, hands-on, senior-level negotiation and support before, during, and long after the transaction.
We retained MidCap to negotiate an unsolicited offer our company received. Following their advice we decided to run a full marketing campaign process.
We retained MidCap to negotiate an unsolicited offer our company received. Following their advice we decided to run a full marketing campaign process. As a result of trusting MidCap’s advice to run a full process, they sourced and executed another deal that was much better aligned with our strategic goals and exceeded any prior valuations way beyond our expectations!
I would highly recommend MidCap Advisors. My dealings with them were always cordial, professional, and steadfast. Our acquisition process ran into com
I would highly recommend MidCap Advisors. My dealings with them were always cordial, professional, and steadfast. Our acquisition process ran into complexities, yet they never lost their focus and ability to advance the conversations to a satisfactory conclusion. I retain the utmost respect for their assistance – especially valuable in a process which can be nerve-wracking and emotional for an individual who has spent over forty years building a company. Their advocacy was immensely valuable.
I couldn’t have asked for a better partner than MidCap. They ran a competitive process that brought in multiple strong bidders and gave us great opt
I couldn’t have asked for a better partner than MidCap. They ran a competitive process that brought in multiple strong bidders and gave us great options. Their team was involved every step of the way, helping us position the company, manage buyer conversations, and get through diligence. Their expertise and genuine care made all the difference and led to a great outcome for our team.
Just like in your business, our people are what make us great

Let’s start a conversation about your company’s strategic goals and vision for the future.
Let’s start a conversation about your company’s strategic goals and vision for the future.
Let’s start a conversation about your company’s strategic goals and vision for the future.
Let’s start a conversation about your company’s strategic goals and vision for the future.
Most owners frame perpetuation as a price problem. The real variable was settled years earlier, and it has nothing to do with the multiple.
Industry Perspective | A three-part series on internal ownership transfer
By Chad Morgan, Vice President at MidCap Advisors
Sooner or later every privately held agency owner answers the same question: sell to the outside, or pass the torch internally. It feels like a question about value. It is almost never decided there.
Internal perpetuation is the gradual, planned transfer of ownership from the principal to the next generation of operators, usually priced at fair market value and paid for over time out of the agency’s own earnings. It remains the most popular stated plan among independent agency owners, and the one most of them never actually complete.
The shortfall between intention and outcome is wide, and it is worth sitting with. Make no mistake: selling externally is often a tremendous strategic win on its own, fueled by active buyers and highly competitive valuations. However, if an owner’s true goal was an internal transfer, abandoning that plan for an external sale usually points to a failure of preparation. This gap is rarely born of negligence – most owners are simply consumed by the daily demands of running the business – and it tends to show up in the exact same place every time.
Owners obsess over the wrong number. The conversation almost always opens with the valuation delta: the spread between what a consolidator would pay today and what an internal buyer can afford. That spread is real, and in a strong market, it can be material. But it is a distraction from the question that actually governs whether an internal deal survives.
That question is quieter and far less flattering to ask out loud: can this agency produce its profit without you in the building? After-tax profit is the only reliable source of financing for your eventual buyout. If profit cannot be sustained in your absence, no structure, no discount, and no clever note rescues the plan. The deal will close and then quietly come apart.
The share of owners who set out to perpetuate internally and actually finish the job, by most industry estimates. The other three usually discover the constraint too late to fix it.
Here is the reality of transition planning, and the reason this series exists. The internal-versus-external choice is often viewed as a strategic decision made at the moment of exit. In truth, it is the cumulative result of decisions made three, five, even seven years earlier, about who was developed, who was trusted with a book, and whether the agency’s income was ever allowed to detach from the founder’s personal relationships.
By the time an owner sits down to weigh internal against external, the menu of available options has already been written. Building a business takes everything you have; it’s no surprise that developing a successor alongside it can be incredibly demanding.
Selling externally is an excellent and highly lucrative path, often providing the ultimate financial reward for a lifetime of hard work. However, owners who invest in building capable successors early on empower themselves with the luxury of choice. They can confidently pursue whichever path – a premium external sale or an internal legacy – best aligns with their goals when the time comes.
Two tests decide everything, and both are about people, not price. Before a single share should change hands, the incoming owners have to clear two bars:
Note what these questions are not. They are not about loyalty, tenure, or how much someone is liked. They are answered by a demonstrated track record, not by hope or by a flattering self-assessment from the candidate. When both answers are a confirmed yes, perpetuation moves from a contingent maybe to an operational decision about timing and structure. When either is a no, every dollar of valuation analysis is premature.
The valuation delta gets the attention because it is concrete and it can be put in a spreadsheet. The succession-capability question often gets avoided because it is awkward and personal. So the easy number crowds out the hard one. That is precisely backwards, and it is the most expensive habit in the entire process.
An owner who runs the hard test first changes the whole posture of the deal. A defined runway before retirement stops looking like a countdown and starts looking like an asset: time to transition client relationships, time to let successors carry real profit-and-loss responsibility, time to build the track record that finances the buyout. The same five years are either a gift or a trap, depending entirely on which question you answered first.
The choice between perpetuating internally and selling externally is not really a choice between two prices. It is a verdict on work that was done, or not done, long before anyone reached for a calculator. The price gap reflects what the market will pay—often an exceptional reward for the business you have built—but it reveals nothing about whether your team can carry the agency the day you step away.
Get that verdict right, and the structure becomes a matter of execution. Get it wrong – by trying to force an internal deal when the team isn’t ready – and the most elegant deal on paper still fails on contact with reality. In those cases, choosing a strategic external sale instead is the right business decision.
If the people are ready, the next failure point is the money. Most internal deals are designed to be self-funding, paid for out of the profit the new owners’ stake generates. Most also break the one rule that keeps them solvent. There is a single ceiling on annual debt service that, once crossed, collapses perpetuation plans after closing more often than any other cause. We will name it, show why owners blow through it, and explain why a deal that leans on the tax deduction of its own purchase price was doomed before the ink dried.
This content is intended for general informational and educational purposes for independent insurance agency owners and does not constitute legal, tax, or investment advice. Specific decisions should be made in consultation with qualified legal, tax, and financial professionals familiar with your circumstances.
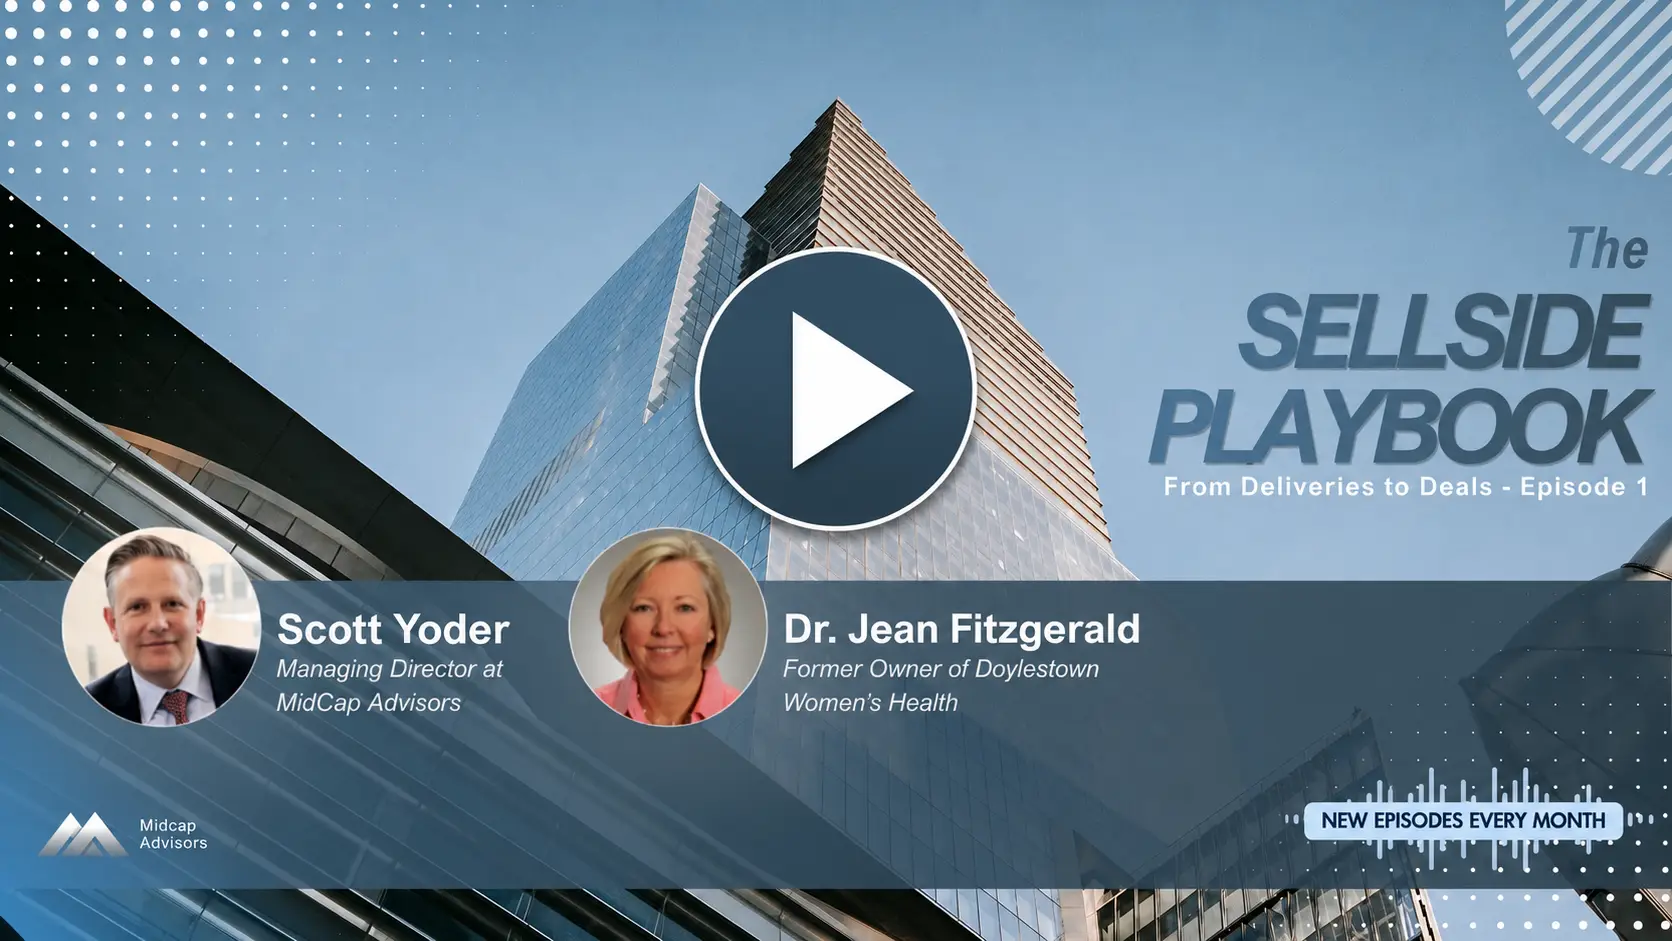
From Deliveries to Deals – Episode 1:
MidCap Advisors’ Managing Director of Healthcare, Scott Yoder, sits down with Dr. Jean Fitzgerald of Doylestown Women’s Health to discuss the journey of building a successful independent OB/GYN practice and the factors that led the group to pursue a strategic partnership. With more than 41 years of experience as a board-certified obstetrician and gynaecologist, Dr Fitzgerald shares insights on navigating the evolving women’s health landscape, managing a competitive sale process, and reflecting nearly two years after closing.
Compensation Is a Valuation Variable: Physician compensation is one of the most complex and consequential elements of an OB/GYN practice valuation. In a transaction, buyers will normalize physician compensation to fair market value (FMV), which means that owner compensation that is either well above or well below market rates will be adjusted in the financial model. For a practice owner who has been drawing a below-market salary to maximize distributions, this normalization can reduce normalized EBITDA, which is unfavorable. But for a practice with multiple physicians compensated at above-market rates, the normalization adjustment will increase EBITDA and increase value. Understanding the relationship between your current compensation structure and the buyer’s normalization process is essential planning knowledge.
Physician retention is among the most significant post-acquisition risks that PE buyers manage in physician practice transactions. A practice in which key physicians are not contractually committed beyond closing poses a material earnings risk that buyers will discount. Most PE-backed transactions include employment agreements for all key physicians that run for 3 to 5 years post-close, with compensation structured to maintain productivity incentives while aligning with the broader platform’s financial targets. Practices that can deliver long-term physician agreements as part of a transaction de-risk the transaction and can earn a meaningful multiple premium.
After a PE-backed sale, physician compensation typically shifts from a simple ownership draw or equal-share model to a layered structure that includes a base salary (usually set below current draw), productivity-based incentives tied to wRVUs or collections, practice-wide profit sharing (EBPC-based), potential equity rollover in the combined platform, and value/quality bonuses tied to outcomes metrics. Understanding this post-transaction compensation architecture before entering negotiations allows physician-owners to model their expected post-close earnings and evaluate deal terms on a fully-loaded basis—not just the headline transaction multiple.
The ideal pre-sale compensation structure aligns physician incentives with practice growth, retains clinical talent during the transition period, and presents buyers with a predictable, scalable earnings model. Achieving that alignment requires thoughtful design, physician buy-in, and ideally external compensation benchmarking data. Engaging a healthcare compensation consultant or transaction advisor in the 12 to 24 months prior to a planned sale is a high-return investment that can pay dividends not only in valuation but in transaction speed and certainty.
A Market Poised for Renewed Momentum: As 2026 unfolds, the women’s health M&A market is entering a period of renewed momentum following two years of calibration and normalization after the 2021-2022 transaction peaks. Multiple macroeconomic and structural forces are converging to support increased deal activity: stabilizing interest rates are improving acquisition financing conditions, record levels of PE dry powder are seeking deployment, improving public equity market conditions are creating a clearer path to future PE exits, and the demographic and structural fundamentals underlying women’s health demand continue to strengthen. KPMG’s 2026 Healthcare & Life Sciences Investment Outlook reports that 67% of healthcare and life sciences dealmakers surveyed anticipated increased M&A activity in 2026.
The nine major PE-backed women’s health platforms operating in the U.S. as of early 2026 are at varying stages of their investment cycles. As platforms mature and PE sponsors approach the end of their typical holding periods, secondary sales, larger strategic combinations, and potential public-market exits via IPOs will become increasingly relevant. The reopening of the healthcare IPO market, with Hinge Health and Omada Health going public in the summer of 2025, signaled renewed investor appetite for healthcare services assets, creating a potential exit pathway for the largest and most mature women’s health platforms. This secondary transaction activity will itself generate new investment opportunities as assets are repositioned and repackaged.
The platforms that will command the highest exit multiples in the next 5 to 7 years will be those that successfully execute multi-specialty expansion strategies. Fertility services, behavioral health integration, menopause and longevity medicine, and AI-enabled diagnostics are the service categories most frequently cited by investors and operators as the highest-priority growth vectors. The global “FemTech” industry, software and technology addressing women’s biological needs, was expected to grow to $75 billion by 2025 at a 13.3% compound annual growth rate since 2020, and its continued expansion is creating new investment and integration opportunities for clinical platforms. OB/GYN practices that are already building out these service lines today will be more attractive acquisition targets for established platforms—and will benefit from higher multiples that reflect the diversified earnings potential.
The regulatory environment for physician practice M&A is increasingly complex. State-level oversight legislation, ongoing federal scrutiny of PE in healthcare, evolving Stark Law and Anti-Kickback enforcement priorities, and continued uncertainty around Medicaid reimbursement policy all represent headwinds that buyers must underwrite, and sellers must understand. PwC’s 2026 healthcare M&A outlook notes that buyers are demonstrating disciplined capital deployment in this environment, favoring high-quality, cash-generating assets with clear reimbursement visibility and avoiding areas subject to shifting regulatory dynamics. For OB/GYN practice owners, the practical implication is clear: a well-run, compliant practice with a diversified, commercially weighted payer mix will be a more attractive and more highly valued transaction target than a comparable practice with compliance risk or payer mix uncertainty.
The most important forecast for independent OB/GYN practice owners is this: the window of maximum investor interest in women’s health is open now, and the practices that engage in strategic planning today will be best positioned to participate on favorable terms. Nine major platforms are being built, hundreds of millions in PE capital are allocated specifically to women’s health acquisitions, and demographic demand for comprehensive women’s health services continues to accelerate. For practice owners who have invested years in building a high-quality, well-run clinical practice, the current environment represents a genuine opportunity to realize that value, with the right preparation, the right process, and the right advisors by their side.
Our Vice President, Tony Leonard, was recently quoted in a Wealth Solutions Report article.
Tony addresses how a financial advisor can help their business owner clientele when succession through M&A is a priority. With a CPA, an attorney, a financial advisor, and an experienced investment banker who can provide end-to-end guidance, these parties can supply business owners with the appropriate resources and advice. Together they will ensure a timely and successful closing of their client’s company.
Our Vice President of Healthcare, Our Team, was featured in a Healthcare Business International article that further speculated about Fresenius’ strategy to offload its expansive fertility asset, The Eugin Group, to the M&A market. It is through the courtesy of Healthcare Business International that we can share this information with our audience.
Robert shared insights related to The Eugin Group’s partnerships with prominent IVF clinics across 3 continents, he assessed the overall U.S. M&A market, and he explained the market from an investor’s perspective. Also, with experience as an administrator and CEO of a hospital, Robert observed that even though European hospitals are selling “non-core” fertility assets, U.S. hospitals are not doing the same currently. Robert cited higher concentrations of older patients with critical needs, nurse shortages, and wage demands as possibilities for why hospitals would need liquidity.
Currently in its 90th year of operation, PMA provides commercial and personal lines customers risk management solutions.
“EMG retained MidCap to identify a qualified buyer with the ideal cultural fit while maximizing enterprise value,” said Douglas Hendrickson, Partner at MidCap, who led the deal team along with MidCap Vice Presidents Brandon Bisack and Michael Gorlick, and Analyst Gabriella Walker. “The ideal buyer had to respect EMG’s entrepreneurial vision to operate independently and retain its full staff while availing itself of the advanced technological resources and elevated marketing opportunities an acquisition could provide. SMS checked all the boxes.”
SMS represents top Medicare Supplement, Medicare Advantage, annuity, life, long-term care, and travel insurance in all 50 states. The firm was founded in 1982 and joined parent firm Alliant Insurance Services in 2020.
From
MidCap Advisors LLC
675 Third Avenue, 28th Floor New York, NY 10017
Contact
NEW YORK, NY – July 29th, 2026 – MidCap Advisors, a leading lower-to middle-market investment bank, announced its role as the exclusive financial
From
MidCap Advisors LLC
675 Third Avenue, 28th Floor New York, NY 10017
Contact
From
MidCap Advisors LLC
675 Third Avenue, 28th Floor New York, NY 10017
Contact
From
MidCap Advisors LLC
675 Third Avenue, 28th Floor New York, NY 10017
Contact